Budget Template for Couples: Two Incomes, One Plan
A good budget template for couples answers three questions: what do we share, how do we split it, and what stays personal? Once those are decided, the rest is arithmetic. This guide covers how to set up a template, with sample numbers, and which choices to make together.
Start with a conversation
A template cannot settle disagreements about money, but it can make them concrete. Before opening a spreadsheet, talk through:
- Shared goals. Rent or a mortgage, savings, a trip, debt payoff.
- Shared bills. Which bills belong to both of you?
- Personal costs. What will each person pay from their own money?
- Fairness. What split feels fair to both?
- Decision rules. For example, any purchase over an agreed amount is discussed first.
Write the answers down. The template will reflect them.
What a couples template needs
| Part | What it does |
|---|---|
| Income for each partner | Take-home pay per paycheck, with each person's pay schedule |
| Yearly income and share | Shows each partner's share of household income |
| Split method | Proportional to income, or 50/50 |
| Shared buckets | Bills and goals both pay into |
| Personal buckets | Costs each person covers alone |
| Totals | What each person owes into the shared pot, per paycheck |
| Remaining | What is left for each person after their share |
Two ways to split shared bills
50/50
Each person pays half of every shared bucket. It is simple and easy to explain. If one partner earns much more than the other, though, the lower earner may feel more strain.
Proportional to income
Each person pays the same percentage of their income toward shared costs. If one partner earns 60 percent of the household total, they cover 60 percent of the shared buckets. It gives each person a similar share of their own pay.
An example with take-home pay of 2,300 for Partner A and 1,900 for Partner B per paycheck, shared bills of 3,000 per month:
| Method | Partner A | Partner B |
|---|---|---|
| 50/50 | 1,500 | 1,500 |
| Proportional (A earns about 55%) | about 1,650 | about 1,350 |
(This ignores different pay schedules to keep the example simple. A full template accounts for them.)
Neither is right for everyone. Some couples use a mix, such as an even split for rent and a proportional split for savings.
Different pay schedules
One partner may be paid weekly, the other biweekly or monthly. The solution is to work in yearly amounts:
- Convert each shared bucket to a yearly cost.
- Work out each person's share of the year (50/50 or proportional).
- Divide each person's yearly share by the number of paychecks they receive per year.
Then each person knows how much to set aside on each of their paydays. A "by paycheck" view is useful here.
Personal money
Many couples keep a personal spending allowance for each person, with no questions asked. It reduces arguments about small purchases. Make it a bucket of its own, with an agreed amount, so it is part of the plan and not an afterthought.
Shared goals and annual costs
Include the costs that arrive rarely: holiday gifts, insurance, vacations, car registration. Setting aside a small regular amount for each, as explained in what are sinking funds, keeps them from causing disagreements when they arrive. For help choosing buckets, see the budget categories list.
A monthly money meeting
A short, regular check-in works better than occasional long ones.
- Frequency: once a month, 20 to 30 minutes.
- Agenda: what we spent against the plan, what changed, upcoming big costs, one adjustment.
- Tone: curious, not accusing. The plan is a shared tool.
Common pitfalls
- Hidden accounts or debts. Honest numbers are the foundation.
- One person doing everything. Both should understand the plan.
- No personal money. It builds resentment.
- Never updating. Income, rent and goals change.
Putting numbers on it: a short walkthrough
Here is how a first session might go for two people who want to build a plan in about an hour.
- Each person writes their take-home pay and pay schedule. One is paid every two weeks and the other twice a month, for instance.
- Together, list the shared buckets: rent or mortgage, utilities, groceries, insurance, a shared savings goal, and the yearly costs such as gifts and travel.
- List the personal buckets separately: phone, hobbies, clothing, and each person's spending money.
- Choose a split method for the shared buckets and try both to see the difference.
- Check the result for each person: after their share and their personal buckets, is anything left, or is someone short? If so, change the split, the buckets or the goals.
- Pick a date for the first monthly check-in.
Treat the first version as a draft. After two or three months of real spending, you will know which numbers were optimistic.
Template included in Bucket Budget Planner
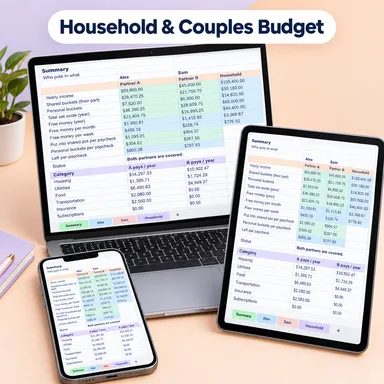
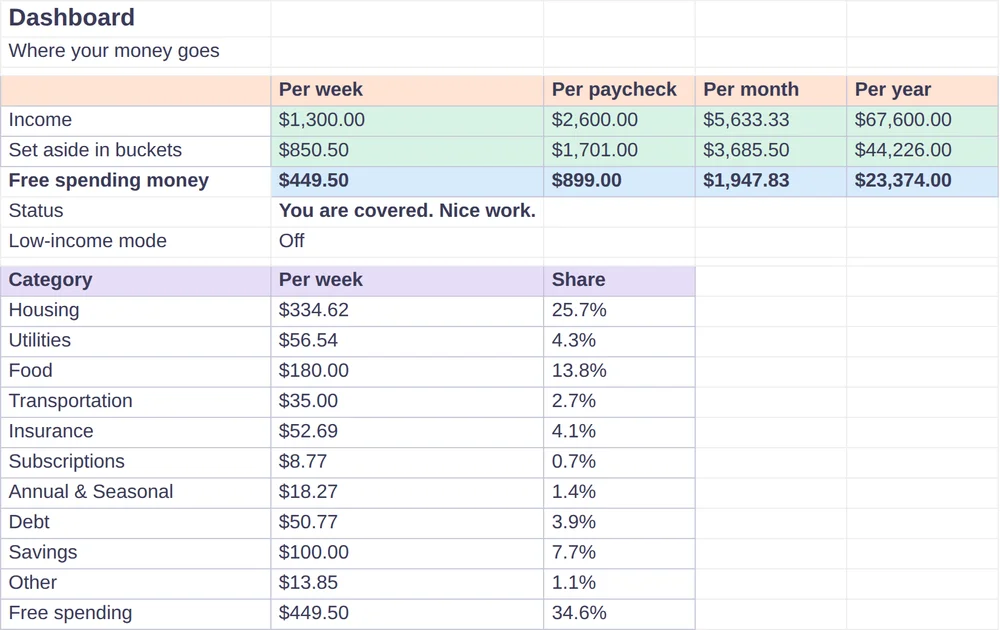
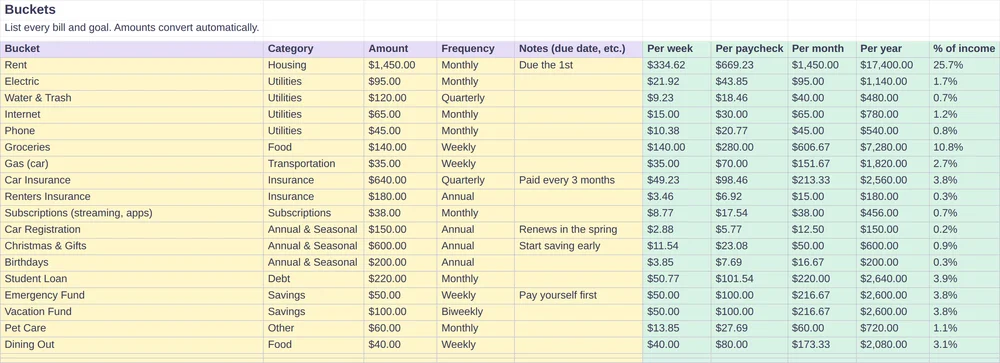
Bucket Budget Planner includes a Household & Couples Budget in Excel. On its Setup tab, you enter each partner's name, take-home pay per paycheck and pay schedule (weekly, biweekly, semi-monthly or monthly), and choose to split shared buckets proportionally to income or 50/50. The Buckets tab lists each bucket as shared or personal, with an amount and frequency, and calculates the yearly, weekly and monthly amounts and how much each partner pays per year. The Summary tab shows who puts in what to the shared pot, personal totals and what is left. The Weekly View and By Paycheck tabs show the same numbers per week and per payday, with each partner on their own pay schedule.
The main Bucket Budget Planner and its library of 154 buckets come with it, and the web app includes a Paycheck Splitter that shows which bills each paycheck covers. Both files import into Google Sheets, and in Google Sheets you can share the file with your partner so both of you see the same live numbers.
For the general method of setting up a paycheck budget, see how to budget a paycheck. To understand buckets, see what is bucket budgeting, and to track what you actually spend each month together, see the monthly spending tracker guide.
This guide is general information, not financial advice. Couples should choose the arrangement that works for their situation.