How to Stick to a Budget When You Keep Falling Off
If you cannot stick to a budget, the problem is usually the budget, not you. Plans fail when they assume a month with no surprises, leave no room for fun, or demand more time than you have. The habits below fix those causes one at a time. Pick two or three, not all nine.
Why budgets fall apart
People who say "I can't stick to a budget" tend to describe the same patterns:
- The plan was built on hope rather than past spending.
- One unexpected bill in week two made the whole month feel ruined.
- Tracking took too long, so it was skipped, then forgotten.
- There was no money for anything enjoyable, so spending came back with a vengeance.
- The budget lived in a place that was easy to ignore.
Look at that list and ask which ones sound like you. That is where to start.
Nine habits that help
1. Base the plan on what you really spend
Pull your last three months of statements and average each category. If you have been spending 600 on groceries, a plan of 350 will not survive the first week. Start with reality and trim gradually.
2. Keep a fun-money line
Give each person a small amount with no rules attached. When there is permission to spend, there is less urge to blow the plan.
3. Use fewer categories
Ten to fifteen is enough. Each extra category is one more number to track and one more way to feel behind.
4. Make the check-in short and regular
A 15-minute weekly session beats a long monthly one. Put it on the calendar at the same time every week. For a method, see how to track spending.
5. Plan for irregular costs
Car repairs, gifts, insurance and annual fees are not surprises; they are late arrivals. List them for the year, divide by twelve and save that amount monthly. A spreadsheet with a yearly view makes this simple. See the budgeting basics.
6. Automate the saving, not the spending
Set a transfer to savings the day you are paid. What you do not see in checking is harder to spend.
7. Build a buffer category
Add a line called "Surprises" with a modest amount. When something unplanned happens, draw from it instead of declaring the budget broken.
8. Reset instead of quitting
If you overspend, adjust the rest of the month. Move money between categories, then carry on. A budget is a tool you steer, not a test you pass or fail.
9. Try a short reset challenge
A no-spend weekend or month can break autopilot spending and show you what you do not miss. See the no-spend challenge guide.
A note on the popular rules
Two rules appear in many searches:
- 50/30/20: about 50 percent of take-home pay for needs, 30 percent for wants and 20 percent for savings and extra debt payments. It is a starting point; your housing costs may push needs higher.
- The 27.40 rule: setting aside 27.40 each day comes to about ten thousand over a year (27.40 times 365). It shows how small daily amounts add up, but it only works if your budget leaves room for it.
Neither rule is advice tailored to you. Use them to test ideas, then build a plan from your own numbers.
What to do in the first week
The first week sets the tone, so keep it light. Do not rebuild your whole financial life. Open your budget file, check that last month's real numbers are in it, and write down the one category that has caused the most trouble. Then decide on a single action for that category: a lower plan, a weekly cash limit, or moving the payment date. Small, specific actions are far easier to repeat than a general promise to "spend less".
If a partner shares your money, agree on the weekly check-in together. Budgets that only one person understands tend to fail when that person is busy. Ten minutes together, with the dashboard open, is enough to keep both of you looking at the same numbers.
Signs your budget needs changing
| Sign | Likely cause | Fix |
|---|---|---|
| Over plan in one category every month | Plan too low | Raise it, take from another category |
| Under plan in most categories | Plan too high | Redirect the extra to savings or debt |
| Skipping logging for weeks | Process too heavy | Cut categories, shorten the routine |
| Big overspending after tight months | Plan too strict | Increase fun money |
Make it visible
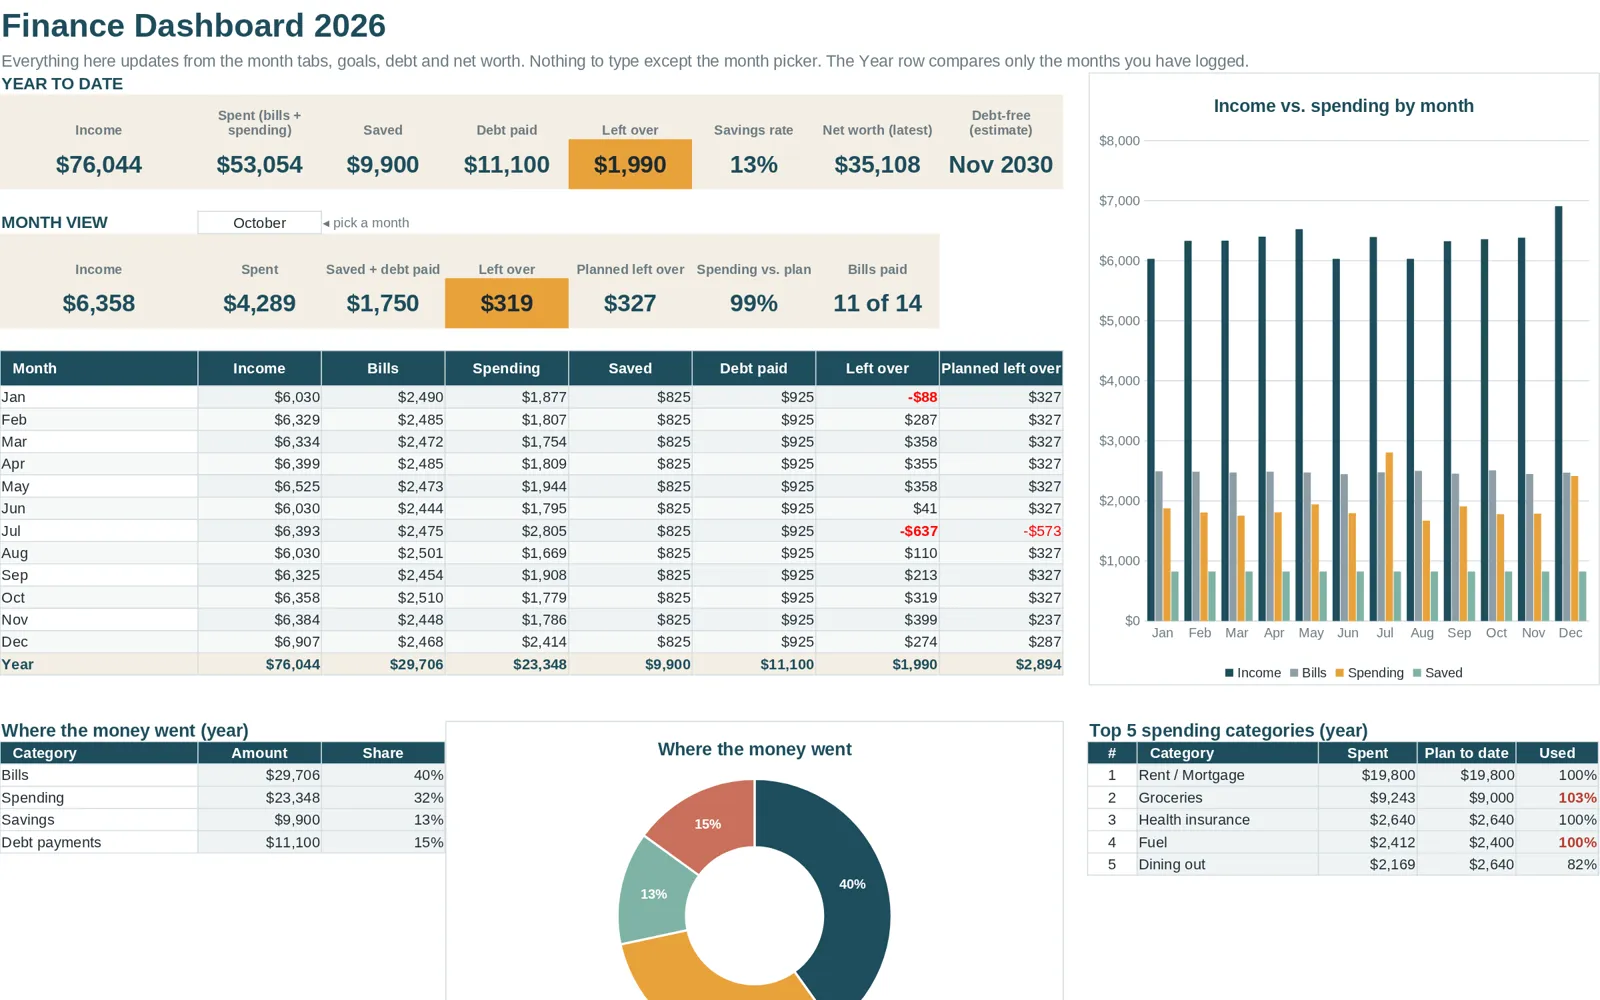
A budget you do not see will not guide you. Keep the file on your phone or desktop, or print a one-page summary. A dashboard that shows how much is left in each category makes the decision before a purchase much easier.
How Clear Budget Planner supports the routine
Clear Budget Planner gives you a Dashboard and Year Summary that show plan versus actual at a glance, twelve monthly tabs with room for up to 150 transactions each, a Bill Tracker so due dates do not sneak up and a Savings Goals tab for the sinking funds mentioned above. The order also includes a No-Spend Challenge Tracker among its bonuses. It is a spreadsheet, not financial advice, and it does the arithmetic so that your weekly check-in stays short.
Start small this week
Choose one change: set your fun money, cut a category or put the weekly check-in on your calendar. Do that for a month, then add another. Habits stick when they are small enough to repeat.